The second-hand market in France in 2026
The used vehicle market in France continues to undergo significant transformations, influenced by economic, regulatory and technological factors. After a year 2025 marked by slight growth, 2026 confirms certain structural trends, while revealing new dynamics. Here is a detailed analysis of recent developments, based on the latest available data.
Market Overview
After slight growth in 2025 (+0.7% registrations), 2026 marks a downturn with a 3.4% decline in sales in July compared to the same period the previous year. This slowdown is part of an economic context marked by persistent inflation and increased caution among households regarding car spending. However, despite this contraction, the second-hand market remains more resilient than the new car market, which is still struggling to return to its pre-pandemic level, with a 26.5% delay compared to 2019.
The average age of registered used vehicles now stands at 11.1 years, compared to 10.6 years in 2024, according to the SDES. This trend is partly explained by the rise in the prices of new vehicles, which is pushing consumers to keep their cars longer or to turn to older used models. Vehicles over 15 years old, which accounted for 30.4% of the market in 2025, are seeing their share increase, while models less than 5 years old are down 6.4%. This development also reflects the economic difficulties of households, which are forced to look for more affordable mobility solutions.
The decline of diesel is accelerating, electric is struggling to break through
The structure of the market by engine is undergoing major upheavals. Diesel, which still dominated the second-hand market a few years ago, continues to decline. In July, it accounted for only 42% of registrations, compared to 51% in 2023. Petrol, now in the majority, accounted for 44% of searches on platforms such as Leboncoin. This shift can be explained by several factors, including recent geopolitical crises, which have caused fuel price spikes. These events have accentuated consumer mistrust of diesel, which is already weakened by environmental restrictions and the extension of low emission zones (LEZs) in major cities.
In this context, there is growing interest in electrified vehicles, but their growth remains limited. In 2025, used electric cars accounted for only 3.3% of registrations, compared to 2.5% in 2024. Their average price, 16% lower than that of new for models less than 3 years old, gradually makes them more accessible.
However, demand is increasingly strong, In the second quarter of 2026, the average resale time for a used electric vehicle was 138 days, compared to 142 days for a combustion model, according to the Mobilians/Avere barometer.
In addition, inventories of electrified vehicles remain tight, with supply struggling to keep up with demand, keeping prices high. For example, the average price of a used Tesla Model 3 increased by 3% in the second quarter of 2026.
Crit'Air and regulations: an increasingly decisive criterion
Environmental regulations are playing an increasing role in consumer choices. In 2025, nearly 40% of used vehicles registered were classified as Crit'Air 1, a category that includes the least polluting models. This proportion, which has been steadily increasing since 2023, reflects the adaptation of buyers to the restrictions imposed by the LEZs, which have now been extended to new cities such as Lyon and Bordeaux. Conversely, vehicles classified as Crit'Air 2 and 3, although still present on the market, could see their residual value deteriorate in the medium term, as standards become stricter.
This regulatory change also has an impact on prices and resale times. The newest and best-ranked models benefit from sustained demand, while older vehicles, which are often more polluting, sell less quickly and at lower prices. For professionals in the sector, this trend highlights the importance of targeting vehicles that comply with environmental standards, in order to limit the risk of depreciation.
Digitalization is the norm, C2C is resisting
The landscape of used vehicle distribution channels is changing rapidly, driven by digitalization and new consumer expectations. In 2025, sales between individuals (C2C) accounted for 47% of the market, according to L'Argus, a stable proportion compared to previous years. This channel remains popular thanks to its accessibility and the search for good deals by buyers. However, sales made by professionals (B2C) retain a significant share, with 43.6% of transactions in 2025. This segment benefits from increased consumer confidence in the warranties and services offered by organized networks, such as certified technical inspections or warranty extensions.
Digitalization plays a key role in this transformation. Buyers are now used to consulting ads enriched with 360° photos, detailed histories and online technical inspection reports. This increased transparency strengthens the competitiveness of professional players in the face of the parallel market. For retailers, the challenge now is to optimize their online presence and offer differentiating services, such as virtual try-ons or home deliveries, in order to attract an increasingly demanding clientele.
Prices and models: a market segmented between opportunities and risks
According to data from La Centrale, the average price of used vehicles has stabilized below the €20,000 mark since 2025. This stabilization corresponds to the maximum budget of the majority of buyers. Vehicles over 16 years old, which accounted for 28% of sales in July 2026, have seen their share increase by 4.9% compared to 2025. Conversely, young used vehicles, less than one year old, are stagnating at 10% of transactions, a sign of a new car market that is slow to fully recover.
In terms of models, consumer preferences are shifting towards compact and fuel-efficient vehicles. In July 2026, the Toyota Yaris, the Fiat 500 and the Dacia Sandero were among the models whose sales grew the most, with increases of 10.64%, 9.97% and 7.45% respectively. These cars, adapted to urban constraints and modest budgets, also benefit from their good Crit'Air classification. On the other hand, models such as the Peugeot 307 or the Mercedes A-Class have seen their sales fall, victims of their age or competition from more recent alternatives.
French brands, traditionally strong in the second-hand market, are experiencing an erosion of their market share. The latter recorded a 4.1% decline in volume in July 2026, in the face of the rise of other manufacturers, but also the timid emergence of Chinese brands, whose share now stands at 0.74% of the market (0.39% in July 2025). Although marginal, the latter could gain in importance as their offer expands and the prices of used Chinese electric vehicles become more competitive.
Outlook for 2027, between renewal of the fleet and energy transition
Several factors will shape the future of the used car market in the coming years. First, the renewal of the car fleet will largely depend on the recovery of the new car market, observed since the beginning of 2026. Vehicles registered today will supply the used car market within three to five years, with an increasing proportion of electrified models. This development could ease the current tensions on the supply of used electric vehicles, whose stocks remain limited.
Secondly, environmental regulations will play a decisive role. The extension of the LEZs and the gradual entry into force of the Euro 7 standard, scheduled for 2025-2030, should accelerate the exit of the most polluting vehicles from the fleet.
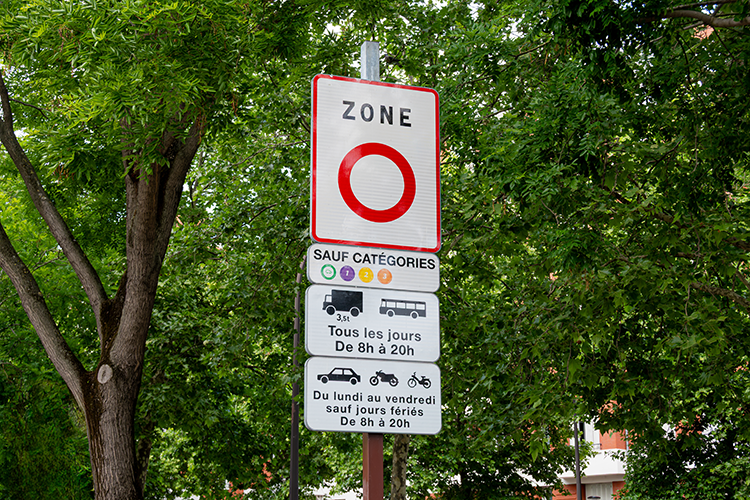
Models classified Crit'Air 3 or not classified could thus see their residual value fall, while Crit'Air 1 and 2 vehicles will benefit from a resale bonus. For professionals, this implies more detailed stock management.
Finally, the evolution of energy prices and household purchasing power will remain key variables. A sustained stabilisation of fuel prices could boost demand for used internal combustion vehicles, while a new geopolitical crisis or a sharp rise in petrol costs could, conversely, accelerate the adoption of electrified models. In this context, market participants will have to remain agile, adapting their supply to fluctuations in demand and regulatory changes.
Conclusion: a rapidly changing market with opportunities
The second-hand market in France in 2026 is characterized by a duality between challenges and opportunities. On the one hand, the contraction in sales, the aging of the fleet and regulatory pressure require professionals to manage risks more rigorously. On the other hand, digitalization, the growing demand for cleaner vehicles and the emergence of new segments, such as used electric vehicles, are opening up growth prospects for those who know how to adapt.
For resellers and rental companies, the keys to success will lie in:
- the targeting of Crit'Air 1 and electrified vehicles, for which demand is expected to grow
- Inventory optimization, with a focus on recent and cost-effective models
- Strengthening customer trust, through extended warranties and increased transparency on vehicle history.